 Australia
 USA
 UK
 Canada
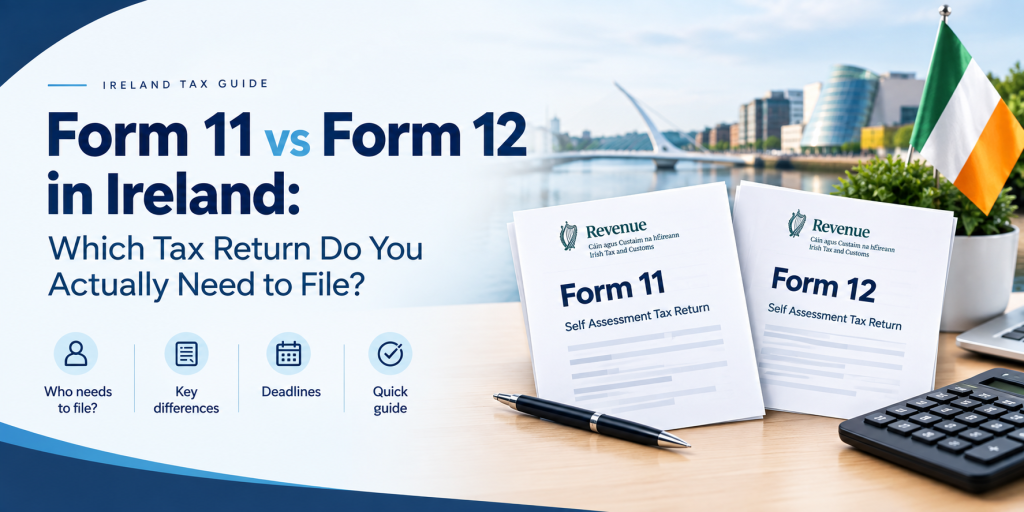

Form 11 and Form 12 govern two distinct tax systems in Ireland. The dividing line is your statutory classification as a chargeable person under Sections 959A and 959B of the Taxes Consolidation Act 1997, as well as Revenue’s Tax and Duty Manual Part 41A-01-01.
Form 12 applies to PAYE employees and pensioners whose untaxed non-PAYE earnings remain below both €5,000 net and €30,000 gross. You file via myAccount, where revenue codes liabilities into future tax credits without preliminary tax.
Form 11 is mandatory for the self-assessed. You enter this regime if non-PAYE income hits €5,000 net or €30,000 gross. Sole traders and proprietary directors holding over 15% share capital must file Form 11 via ROS, regardless of profit or loss, alongside mandatory advance preliminary tax payments.
Submitting Form 12 when legally required to file Form 11 invalidates your return, triggering statutory surcharges up to 10% (capped at €63,485) and daily interest on unremitted tax.
| Taxpayer Status | Required Form | Filing Platform | Preliminary Tax Obligation |
| PAYE employee or pensioner, no other income | Form 12 (optional, mainly for credit claims) | myAccount | No |
| PAYE plus side income (under €5,000 net and under €30,000 gross) | Form 12 | myAccount | No, coded into future tax credits |
| Sole trader or independent contractor | Form 11 | ROS | Yes, mandatory |
| Landlord or investor at or above €5,000 net or €30,000 gross | Form 11 | ROS | Yes, mandatory |
| Proprietary director, more than 15% shareholding | Form 11 | ROS | Yes, mandatory |
| Employee director, 15% or less, under thresholds | Form 12 | myAccount | No |
What Is Form 11?
Form 11 is the statutory annual return for individuals subject to Ireland’s self-assessment tax regime. You submit it electronically through the Revenue Online Service (ROS), and it consolidates multiple tax obligations into a single annual assessment.
A Form 11 filing captures four distinct statutory charges:
- Income Tax: Calculated across trading profits, professional fees, untaxed dividends, foreign income, and gross rents after allowable deductions.
- Pay Related Social Insurance (PRSI): Assessed at Class S for self-employed individuals and proprietary directors. The rate is 4.20% through 30 September 2026 and increases to 4.35% from 1 October 2026, creating a blended rate of 4.2375% for the 2026 tax year. It has a €5,000 income floor and a €650 minimum annual contribution.
- Universal Social Charge (USC): Applied across all assessable global profits based on standard statutory bands, plus an additional 3% USC surcharge on self-employed or non-PAYE income exceeding €100,000.
- Preliminary Tax: A mandatory advance payment toward the current tax year, submitted concurrently with the final balance of the prior year.
Including Preliminary Tax separates Form 11 from standard PAYE filings. When you file a Form 11, you do not simply settle what you owe for the previous calendar year. You must also satisfy one of three preliminary tax rules: pay 100% of the previous year’s liability, 90% of the current year’s liability, or 105% of the preceding year’s liability (available when paying by monthly direct debit through ROS). Sole traders, active business partners, farmers, proprietary directors, and investors with significant untaxed investment yields must complete this process every year.
What Is Form 12 (PAYE Income Tax Return)?
Form 12 is the tax return designed for individuals whose income is taxed almost entirely at source through the PAYE system. While historic paper filings used the physical Form 12, the electronic version is called the PAYE Income Tax Return in Revenue’s myAccount portal.
This return serves two main purposes:
- Claiming unallocated tax credits and reliefs, including medical expenses, third-level tuition fees, and the residential Rent Tax Credit.
- Declaring small sources of untaxed non-PAYE income, such as occasional freelance earnings, modest dividend distributions, or minor deposit interest, provided total earnings sit below statutory chargeable person thresholds.
The settlement mechanism under Form 12 prevents cash-flow shocks. When you submit your return through myAccount, Revenue calculates your liability and automatically codes the outstanding balance into your future tax credit certificates. Revenue collects the underpayment through reduced monthly take-home pay over one to four years, provided the liability remains under €6,000. Alternatively, taxpayers can clear the balance immediately using a debit card or single debit instruction. Preliminary tax does not apply to Form 12 filers.
The Real ‘Chargeable Person’ Test (Where Most Guides Get It Wrong)
Most summaries state that earning under €5,000 in secondary income exempts you from self-assessment. That is only half the law. Under Sections 959A and 959B of the Taxes Consolidation Act 1997 and Revenue’s Tax and Duty Manual Part 41A-01-01, Revenue applies a dual threshold: you are a chargeable person if you breach either test.
Gross Receipts vs Net Assessable Income
- Net Income: Actual taxable profit remaining after allowable business expenses and capital allowances.
- Gross Income: Note that while many practitioners use total turnover before any expenses, Revenue’s Tax and Duty Manual Part 41A-01-01 technically defines gross income as profits before capital allowances and losses carried forward (normal operating expenses already deducted). Flag that readers close to €30,000 should seek advice.
The Dual Threshold: Net €5,000 vs. Gross €30,000
You become a chargeable person if you meet either of the following independent criteria:
- Net Assessable Limit (€5,000): Your net taxable non-PAYE profit, calculated after deducting allowable business expenses, capital allowances, and qualifying reliefs, is €5,000 or more.
- Gross Receipts Limit (€30,000): Your total non-PAYE turnover is €30,000 or more, before subtracting any costs, depreciation, or allowable deductions.
If capital allowances or trade losses reduce your non-PAYE profit down to nil, you remain a chargeable person required to file Form 11, because Revenue cannot code a nil balance into PAYE tax credits.
Income Aggregation Across Sources
Revenue adds together all non-PAYE earnings received during the calendar year. Combine gross rental receipts, freelance fees, untaxed dividends, foreign income, and trading profits. For example, earning €18,000 gross from rental property and €14,000 gross from freelance consulting totals €32,000 gross.
Because the combined figure exceeds €30,000, you are a chargeable person and must file Form 11, even if net profit remains under €5,000. This aggregation also includes deposit interest where DIRT was deducted at source.
Excluded Income
Revenue ignores only two specific types of income when testing the thresholds:
- Payments from the Department of Social Protection
- Legally enforceable maintenance payments received
All other untaxed earnings—including deposit interest, even if DIRT was already deducted—count toward the limits.
Joint Assessment for Married Couples
Under joint assessment, a couple is treated as a single tax unit:
- Shared Filing: If one partner is a chargeable person, the couple must file a Form 11 covering both incomes.
- The Director Trap: If your spouse is a proprietary director (owning over 15% of a company), you must file a Form 11 too—even if you only earn a standard PAYE salary. (Note: this does not apply if the company qualifies under Revenue’s dormant-company exemption detailed below.)
- How to Avoid It: To keep PAYE income separate, apply in writing for separate assessment or single treatment by 31 March of that tax year, not at the autumn filing deadline.
Case Study: The High-Turnover, Low-Net Trap
David earns an €85,000 PAYE salary and runs a side consulting business:
- Gross Billings: €36,000
- Running Costs: €2,000
- Capital Allowances & Past Losses: €32,000
- Net Taxable Profit: €2,000
David assumes he can use Form 12 via myAccount because his €2,000 profit is well under the €5,000 net limit.
That is incorrect. His gross earnings exceed the €30,000 limit whether you look at total sales (€36,000) or profit before capital allowances (€34,000). In addition, Revenue cannot code a nil or low balance wiped out by allowances into his PAYE tax credits. Under Section 959B TCA 1997, David is a chargeable person: he must register for income tax, file Form 11 via ROS, and pay preliminary tax.
Company Directors: It Is Not Automatic for Everyone
By law, every company director must file a tax return. However, Revenue makes an exception in its guidelines for non-proprietary directors (those owning 15% or less), though it notes this rule could change. Your filing route depends on equity control under Section 472(1) of the Taxes Consolidation Act 1997.
The Proprietary Director Rule (>15% Shareholding)
Controlling or owning strictly more than 15% of a company’s ordinary share capital classifies you as a proprietary director and a statutory chargeable person.
Mandatory ROS Filing: You must file Form 11 annually, even if you pay entirely through PAYE and the company makes no profit.
Dormant Exception: Under revenue guidelines, proprietary directors are exempt from Form 11 only if the company meets three strict conditions for the three years ending 31 December of that tax year:
- Held no assets except cash on hand or on deposit of €130 or less,
- Carried on no trade, business, or activity (including investments), and
- Paid no charges on income.
Crucially, this exemption also protects the director’s jointly assessed spouse. If the company meets all three dormant criteria and neither partner has other non-PAYE income breaching the €5,000 net / €30,000 gross limit, neither spouse is forced to file Form 11.
When Employee Directors Can Stick to Form 12
Holding 15.0% or less makes you a non-proprietary employee director. You stay on Form 12 via myAccount provided:
- Remuneration is taxed exclusively at source via PAYE.
- Non-PAYE income remains below both statutory thresholds (€5,000 net and €30,000 gross).
Holding exactly 15% does not breach the rule; the statutory trigger requires ownership exceeding 15%.
Clarifying Corporate Tax: Form 11 vs CT1
Personal and corporate liabilities operate in distinct legal silos:
- Form 11: Reports your individual income, personal reliefs, PRSI Class S, and Preliminary Tax.
- Form CT1: Reports company trading profits taxed at 12.5% or non-trading passive income taxed at 25%. The company itself is the legal entity.
For example, a proprietary director owning 100% of an engineering consultancy must manage both filings. The company submits Form CT1 to pay corporation tax on net business profits. Separately, the director must submit Form 11 to declare their director salary, taxable benefits-in-kind (BIK), company dividends, and personal preliminary tax. Submitting the company CT1 does not satisfy the director’s statutory duty to file Form 11. Omitting the personal return triggers individual late-filing surcharges and compliance action.
Form 11S and Form 12S: The Short-Form Paper Alternatives
Form 11S and Form 12S are condensed, four-page paper returns that Revenue designed for straightforward personal tax scenarios.
Form 11S:
Revenue issues this paper form directly to selected self-employed individuals with basic trading profiles. It omits complex panels covering foreign income, proprietary share schemes, and specialised capital allowances.
However, taxpayers subject to mandatory e-filing under statutory regulations cannot choose to file Form 11S. Because nearly all self-employed professionals, landlords, and commercial operators must file electronically, Form 11S is limited to individuals with a formal, written exemption from online filing granted by Revenue.
Form 12S:
This simplified paper document is provided to PAYE employees and pensioners who are exempt from digital myAccount filing and have uncomplicated affairs. It covers routine items such as PAYE wage verification, single-trade small secondary earnings, and standard medical or flat-rate expense claims.
If you access your taxes digitally through ROS or myAccount, you will never complete an 11S or 12S. ROS will serve you the electronic Form 11 panels based on your tax registration, while myAccount provides the digital PAYE Income Tax Return.
How and Where to File (ROS vs myAccount)
Revenue maintains two separate digital platforms. Choosing the wrong portal or delaying registration exposes taxpayers to serious filing defaults.
The ROS Digital Certificate Trap (Why You Can’t Wait Until October 30)
ROS is Revenue’s commercial portal for self-assessed individuals and corporate entities. Registering for ROS requires three distinct administrative steps that carry a mandatory lead time of 7 to 14 working days:
- Application: You apply for a ROS Access Number (RAN) online.
- Postal Verification: Revenue issues an activation code through an official letter sent by physical post to your registered residential address.
- Digital Certificate Installation: You enter the activation code online, establish system passwords, and download an encrypted digital certificate file (a .p12 file) to your computer.
Leaving your self-assessment setup until late October makes missing the deadline almost inevitable. Without an active ROS digital certificate installed on your browser, you cannot access or submit Form 11.
The MyAccount Guided Workflow
Accessing the PAYE Income Tax Return via myAccount requires no special software or digital certificates. Registration takes minutes using your PPSN, date of birth, and mobile number.
Once logged in, navigate to Manage Your Tax and select Review Your Tax 2022–2025 to open the relevant year. The workflow functions as a pre-populated interview:
- Income Verification: Payroll earnings, statutory deductions, and taxable state benefits flow directly from employer submissions. You simply confirm these figures.
- Non-PAYE Additions: Input ancillary earnings like casual freelancing or deposit interest, provided totals remain below the statutory dual threshold.
- Credit Claims: Claim available reliefs, including health expenses, nursing home fees, and the Rent Tax Credit.
Revenue calculates your final balance instantly, with no preliminary tax calculations required.
2026 Deadlines and Penalties: What Happens If You Are Late?
Ireland operates strict filing cut-offs, pairing immediate statutory percentage surcharges with non-negotiable monetary caps under Section 1084 of the Taxes Consolidation Act 1997. The autumn 2026 deadlines cover your final return and balancing liability for the 2025 tax year, as well as your advance preliminary tax payment for the 2026 tax year.
Key Filing Dates (Paper 31 Oct vs ROS Extended Deadline)
- Paper Filing Deadline: Saturday, 31 October 2026. Because 31 October falls on a Saturday, paper filers must ensure physical forms reach Revenue by Friday, 30 October 2026. Revenue does not extend statutory dates because a deadline falls on a weekend.
- ROS Pay & File Deadline: Wednesday, 18 November 2026. Taxpayers who file Form 11 and pay their prior-year tax balance and current-year preliminary tax exclusively through ROS receive an extended deadline. Both actions must occur through ROS; paying via EFT outside ROS while filing online invalidates the extension and defaults your statutory deadline back to 31 October 2026.
Statutory Late Filing Surcharges (TCA 1997 s.1084)
Late submission of Form 11 triggers mandatory statutory surcharges under Section 1084 TCA 1997:
| Delay Duration | Statutory Surcharge Rate | Maximum Statutory Cap |
| Filed within 2 months (up to 31 December 2026) | 5% of final tax liability | € 12,695 |
| Filed over 2 months late (From 1 January 2027 onwards) | 10% of final tax liability | € 63,485 |
Surcharges apply differently depending on your tax profile:
- General Taxpayers: For sole traders and individual investors, the 5% or 10% surcharge is calculated on net tax remaining after deducting tax credits and PAYE deducted at source.
- Proprietary Directors: Under Section 1084 TCA 1997, the surcharge is calculated on your gross tax liability before deducting PAYE paid through payroll. A director with €30,000 in PAYE deducted at source who files more than two months late faces a 10% surcharge on the entire €30,000, creating an immediate €3,000 out-of-pocket penalty even if zero balancing tax is owed.
Filed the Wrong Form? What to Do Next
Submitting Form 12 when you qualify as a chargeable person invalidates your return. Revenue cross-matches data from the RTB, banks, and the CRO. If flagged, Revenue can treat your return as unfiled, apply late surcharges up to 10%, and demand backdated Preliminary Tax with daily interest.
Revenue Detection and Enforcement
Revenue’s automated systems continuously cross-reference returns against third-party records:
- Residential Tenancies Board (RTB) tenancy registrations
- Companies Registration Office (CRO) director shareholdings
- Bank interest and dividend distributions
- Card processing and online platform reporting
When Revenue identifies that a Form 12 filer breached the €30,000 gross or €5,000 net threshold, or held more than 15% shareholding, they cancel the Form 12 assessment, issue a formal demand for Form 11, apply late-filing surcharges, and charge daily statutory interest on missed Preliminary Tax.
Step-by-Step Rectification and Timelines
Correcting your profile takes between two and three weeks:
- Submit Form TR1: Register for Income Tax via eRegistration on myAccount or post a paper TR1. Note that online eRegistration via myAccount is processed rapidly.
- Obtain ROS Access: Apply for a ROS Access Number (RAN). Revenue posts an activation code to your registered address, which takes 7 to 14 days. Once received, install your ROS digital certificate.
- Submit Overdue Form 11: File the full return via ROS and remit your outstanding liability plus preliminary tax.
Unprompted vs Prompted Disclosures
How revenue penalises the error depends on who initiates contact under the Code of Practice for Revenue Compliance Interventions:
- Unprompted Disclosure: You notify Revenue via myEnquiries before they send an audit or inquiry letter. Unprompted disclosures reduce penalties to the lowest statutory mitigation band and protect against publication on the tax defaulters list, but daily statutory interest (0.0219%/day) still applies. The 10% to 50% penalty range on prompted disclosures applies specifically to a qualifying disclosure; non-qualifying penalties are significantly higher.
- Prompted Disclosure: You correct the filing only after receiving a revenue inquiry letter. Penalty mitigation is strictly limited, and statutory penalties range from 10% to 50% of the unpaid tax.
When to Involve an Accountant
If the error covers multiple tax years, gross income above €30,000 with complex expense claims, or proprietary directorships with company loan accounts, engage a qualified tax advisor immediately. An accountant will calculate your exact exposure, submit an unprompted disclosure to help mitigate penalties, and file your Form 11 returns correctly on ROS.
Get Expert Self-Assessment Support
Navigating the line between Form 11 and Form 12 requires strict attention to statutory thresholds, accurate allowable expense deductions, and absolute compliance with ROS filing windows. Miscalculating preliminary tax payments or missing the ROS setup period can trigger immediate 5% to 10% surcharges alongside recurring daily interest penalties.
Aone Outsourcing Solutions provides direct Irish personal tax compliance for landlords, proprietary directors, contractors, and business owners. Our specialist tax team handles complete income tax registrations, allowable expense reviews, and timely pay & file submissions via ROS, ensuring your filings remain compliant and insulated from revenue intervention.
Speak with our personal tax team today to review your filing status and secure full compliance:
Explore Our Irish Self-Assessment Tax Services
Frequently Asked Questions (FAQs)
Is Form 11 the same as self-assessment?
Yes. Form 11 is the statutory return used to calculate and report liabilities under the Irish self-assessment regime. It covers income tax, PRSI Class S, USC, and mandatory preliminary tax.
Do all company directors have to file Form 11?
No. Under Section 472(1) TCA 1997, only proprietary directors who control or own more than 15% of ordinary share capital must file. Non-proprietary directors owning 15% or less who earn strictly under PAYE can use Form 12, provided other non-PAYE earnings remain under the dual threshold.
Can I switch from Form 12 to Form 11 mid-year?
You do not switch mid-year because returns are filed retrospectively for the prior calendar year. If your current-year non-PAYE income crosses €5,000 net or €30,000 gross, submit Form TR1 to register for income tax before the annual October deadline.
What is the Form 11 deadline for 2026?
The standard paper deadline is 31 October 2026. If you file your return and pay both prior-year balances and current-year preliminary tax through ROS, the deadline is extended to Wednesday, 18 November 2026. Note that paper filing on Saturday, 31 October 2026, requires delivery by Friday, 30 October 2026, and that the return covers the 2025 tax year.
Do I have to pay the preliminary tax the first time I file a Form 11?
Yes. First-time filers must pay preliminary tax. You satisfy the statutory requirement by choosing one of three options: pay 100% of your prior-year liability, pay 90% of your estimated current-year liability, or pay 105% of the pre-preceding year’s liability (available when paying by monthly direct debit through ROS). If your taxable income in the preceding year was zero, your legal payment under the 100% rule is nil, but you must still declare that election on your ROS return.
If my non-PAYE income drops below €5,000 next year, can I go back to Form 12?
If the income source ceased entirely (e.g., you sold the property or ceased the trade), you can formally deregister via myEnquiries and return to Form 12. If the income source continues, you cannot switch back. Once you are a chargeable person for an active income stream, you remain one in subsequent years even if profit drops below €5,000 net or €30,000 gross. You must continue filing Form 11 via ROS while that source exists.